
Fix & Flip Loans
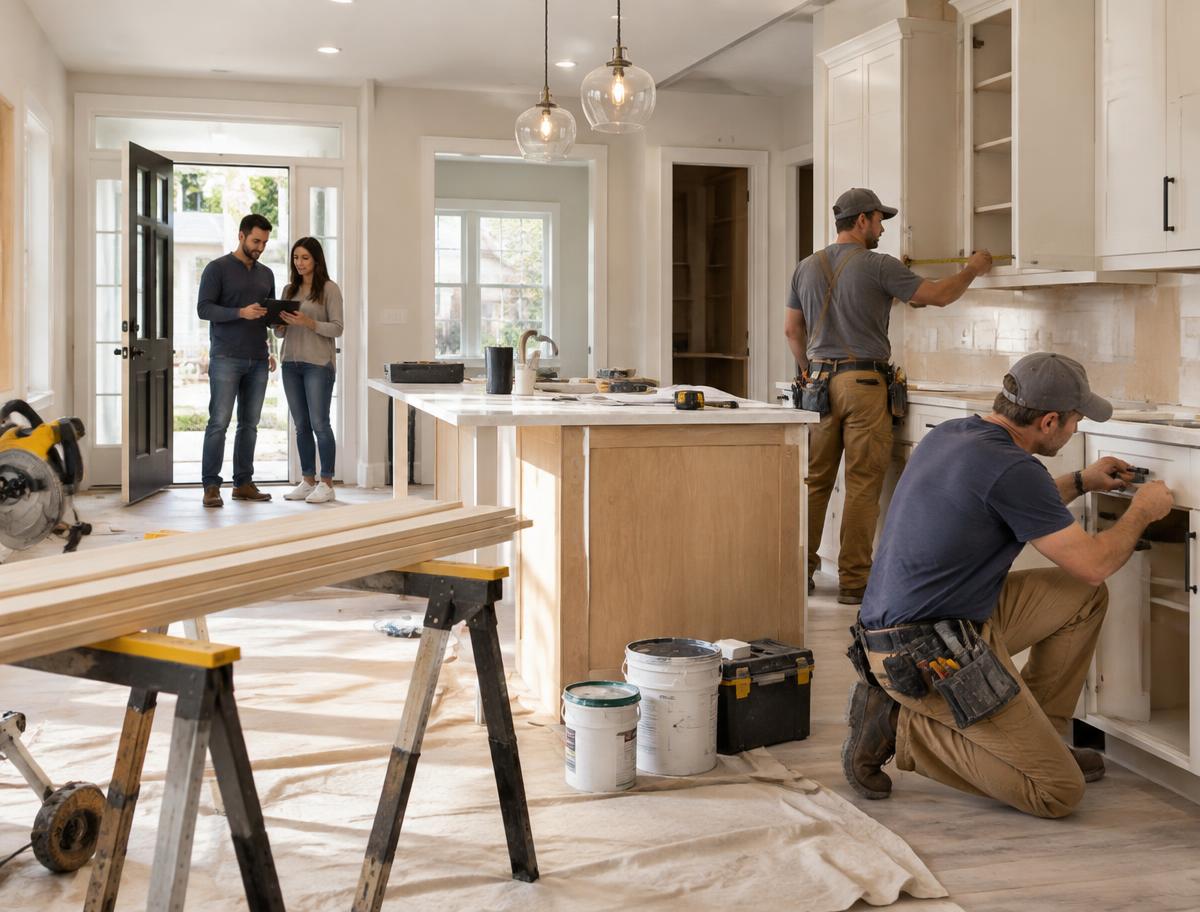
What is a fix & flip loan and who qualifies?
Short-term acquisition + rehab capital for investors. Fix & Flip loans give real estate investors the acquisition and rehab capital needed to buy distressed properties, renovate them, and sell for profit — typically within 6–12 months.
Reviewed and updated August 31, 2026
- 12-month interest-only loan for buy-renovate-sell (or BRRRR-refinance).
- Up to 95% of project cost, 100% of rehab, capped at 75% ARV.
- 10-day closings with proof-of-funds issued same day once your file and asset docs are in letters for auctions.
- No prepayment penalty — pay off any time inside the term.
Short-term acquisition + rehab capital for investors.
Fix & Flip loans give real estate investors the acquisition and rehab capital needed to buy distressed properties, renovate them, and sell for profit — typically within 6–12 months.
Get your Fix & Flip Deal Analysis.
Send us the property and rehab budget — we send back a full flip underwriting: ARV, max loan to purchase, 100% rehab draw schedule, projected profit, and cash-on-cash return.
- ARV & max loan to purchase (up to 90% LTP)
- 100% rehab budget with draw schedule
- Projected net profit & margin
- Cash-on-cash and annualized return
Illustration only, generated from the information you enter. Not a loan estimate, pre-qualification, commitment to lend, or approval. Formal pricing, LTV, and terms are issued only after credit review, income/asset documentation, and full underwriting.
What a fix & flip loan is
A fix & flip loan — often called a hard-money or bridge rehab loan — is short-term interest-only financing designed for investors who buy distressed property, renovate it, and either resell (flip) or refinance and hold (BRRRR) within 6–12 months. Purchase funds close at settlement; rehab funds sit in escrow and release in draws against inspection.
The three leverage limits
Three caps apply simultaneously and the tightest one wins:
- Loan-to-cost (LTC): up to 95% of total project cost on cosmetic rehabs for investors with 6+ completed projects (90% on structural rehabs).
- Rehab funding: up to 100% of the approved renovation budget, released in draws.
- ARV (After-Repair Value): total loan capped at 75% of the appraised as-repaired value.
Example: $200K purchase + $50K rehab, ARV $340K. 90% × $200K = $180K purchase advance; 100% × $50K = $50K rehab; 75% × $340K = $255K ceiling. Total exposure $230K — within the $255K ARV cap. Deal works.
Who this fits
Full-time flippers, BRRRR investors, auction buyers who need 10-day certainty, and part-time investors with 1–2 completed exits per year. Maximum leverage (up to 95% of cost on cosmetic projects) requires 6+ completed projects in the last 36 months and a 700 FICO. First-time investors can still qualify on cosmetic, non-structural rehabs at lower leverage — typically 80% of total cost, 100% of rehab, 65% of ARV (70% with one completed exit) — with a 720 FICO and a rehab budget under $250,000. Structural or gut-rehab projects require at least 2 completed projects in the last 3 years, one of them structural, plus a licensed general contractor.
Rehab financing is not available in Arkansas, North Dakota, New Hampshire, South Dakota, or Vermont, and Alaska and Hawaii are exception-only.
Rates & fees
Rates typically run 9.5%–13.5% depending on experience, leverage, and market. Origination fees are 1.5–2.5 points. Interest is charged only on the drawn balance — you don't pay interest on rehab funds still sitting in escrow. No prepayment penalty at any point.
How BRRRR works with this loan
If you plan to hold, stabilize the property (finish rehab, place a tenant, season the lease 30–90 days depending on the DSCR program), and refinance into a 30-year DSCR loan. Same lender = same file = faster and cheaper takeout. The appraisal from the bridge is often re-usable.
Illustrative only. Not a quote or commitment to lend.
Get your Fix & Flip Deal Analysis
Send us the property and rehab budget — we send back a full flip underwriting: ARV, max loan to purchase, 100% rehab draw schedule, projected profit, and cash-on-cash return.
- ARV & max loan to purchase (up to 90% LTP)
- 100% rehab budget with draw schedule
- Projected net profit & margin
- Cash-on-cash and annualized return
Illustration only, generated from the information you enter. Not a loan estimate, pre-qualification, commitment to lend, or approval. Formal pricing, LTV, and terms are issued only after credit review, income/asset documentation, and full underwriting.
Why investors choose this Fix & Flip loan program
Auction-ready fast closes with proof-of-funds letters same day.
Up to 100% of the budget funded on inspector-verified draws.
Sell whenever the flip is ready — no exit fee.
Roll straight from bridge into a DSCR loan for hold — same lender, one file.
Get your Fix & Flip Deal Analysis
Send us the property and rehab budget — we send back a full flip underwriting: ARV, max loan to purchase, 100% rehab draw schedule, projected profit, and cash-on-cash return.
- ARV & max loan to purchase (up to 90% LTP)
- 100% rehab budget with draw schedule
- Projected net profit & margin
- Cash-on-cash and annualized return
Illustration only, generated from the information you enter. Not a loan estimate, pre-qualification, commitment to lend, or approval. Formal pricing, LTV, and terms are issued only after credit review, income/asset documentation, and full underwriting.
Fix & Flip qualifications at a glance
Program guidelines vary by investor. These are typical ranges — a Loan Officer confirms exact numbers on your scenario.
| Requirement | Typical | Notes |
|---|---|---|
| Minimum credit score | 660 (700–720 for max leverage) | 720 required for first-time investors. |
| Purchase / cost leverage | Up to 95% LTC (cosmetic), 90% LTC (structural) | 80% LTC for first-time investors. |
| Rehab funding | Up to 100% of budget | Released in 2-week draws; 10% contingency required. |
| ARV cap | Up to 75% | 65–70% for first-time investors. |
| Term | 12–24 months IO | Terms over 15 months require management approval. |
| Experience | None on cosmetic; 2+ projects on structural | 6+ projects unlock max leverage. |
| Reserves | 5% of holdback plus any borrower-funded budget | |
| Loan amount | $100K – $3M | Loans over $1M require committee approval. |
| Property types | 1–4 unit residential, PUD, warrantable condo | Non-warrantable condo = 5% LTV reduction; rural, multifamily, mixed-use, manufactured and condotels ineligible. |
| Prepayment penalty | None | Sell or refi any time. |
Ranges are typical program guidelines and vary by investor, credit tier, and market. Not a commitment to lend.
Fix & Flip loan use cases
- Single-family flips
- 2–4 unit value-add flips
- Auction / trustee-sale acquisitions
- BRRRR strategy (bridge into DSCR)
Get your Fix & Flip Deal Analysis
Send us the property and rehab budget — we send back a full flip underwriting: ARV, max loan to purchase, 100% rehab draw schedule, projected profit, and cash-on-cash return.
- ARV & max loan to purchase (up to 90% LTP)
- 100% rehab budget with draw schedule
- Projected net profit & margin
- Cash-on-cash and annualized return
Illustration only, generated from the information you enter. Not a loan estimate, pre-qualification, commitment to lend, or approval. Formal pricing, LTV, and terms are issued only after credit review, income/asset documentation, and full underwriting.
Fix & Flip rate & market update
Compiled from Freddie Mac PMMS, U.S. Treasury, and BLS releases. Figures are published with the period they cover and the date they were retrieved.
Fix and flip loan calculator: LTV, ARV, rehab, carry & profit
Model the three leverage caps every fix and flip loan has to clear (Purchase LTV, Rehab %, and ARV), estimate your interest-only carry during the rehab, and preview net profit after selling costs. Use it before writing an offer or bidding at auction.
Deal inputs
Cost & exit
Selling costs typically run 6–9% (agent commissions, transfer tax, title, minor concessions). Rehab draws are inspector-verified — interest is charged only on drawn balances.
Results
- Purchase advance
- $180,000
- Rehab escrow
- $50,000
- ARV ceiling
- $255,000
- Total loan (binding)
- $230,000
- Cash down at close
- $20,000
- Origination fees
- $4,600
- Est. monthly IO carry
- $1,810
- Total interest over hold
- $10,863
- Projected sale proceeds
- $82,800
- Estimated gross profit / ROI
- $47,338 (133.5% on cash-in)
90% × purchase price.
Released in inspector-verified draws.
75% × ARV — hard cap.
Binding limit: LTC / rehab.
Purchase price − purchase advance.
2 pts × total loan.
Avg drawn balance × 11% ÷ 12.
6 months at current draw pace.
ARV $340,000 − selling costs $27,200 − loan payoff $230,000.
Strong margin — this deal pencils on our current program.
Illustrative only. Not a quote, lock, or commitment to lend. Final purchase LTV, rehab %, ARV cap, rate, points, and reserves are determined in underwriting based on credit, investor experience, property, market, and program overlays in effect at lock.
The 70% rule for flip deals
Every flip file we underwrite works backwards from ARV. If the deal doesn't clear the 70% rule after real rehab + holding + selling costs, it usually doesn't cash-flow on the flip either.
MAO = (ARV × 70%) − rehab − holding − selling − target profit
Example: ARV $300K × 70% = $210K. Rehab $50K, holding $8K, selling costs $24K, target profit $30K. MAO = $210K − $50K − $8K − $24K − $30K = $98K. Pay more than that and margin gets thin fast.
- • Tight MLS inventory with strong absorption (<30 day DOM)
- • Turnkey scope (cosmetic-only, no MEP/structural)
- • Experienced flipper (5+ documented exits)
- • Locked-in GC contract with GMP + 10% contingency
How rehab draws are released
Acquisition funds at close (up to 90% LTP). The rehab budget is held back and released in inspector-verified draws — you never front the full rehab out of pocket.
| Milestone | % of rehab budget | What triggers release |
|---|---|---|
| Close & mobilization | 0% | Acquisition funded at close (up to 90% LTP). Rehab holdback funded post-close in draws. |
| Demo, framing repairs, roof | 20% | First inspection after demo and structural / roofing work complete. |
| MEP rough-in (plumbing, electrical, HVAC) | 25% | Rough-ins inspected and signed off before drywall. |
| Drywall, insulation, exterior | 20% | Drywall hung and finished, exterior paint / siding complete. |
| Interior finishes (kitchen, baths, floors) | 25% | Cabinets, counters, flooring, trim, paint, fixtures installed. |
| Punch list & final | 10% | Punch list complete, final inspection passed, ready to list. |
From close to sale — a typical 4–6 month flip
Most cosmetic-to-moderate flips run 3–5 months on rehab plus 30–60 days on the market. Heavier scope adds 60–90 days.
- M 0Close & fund
Acquisition funded, rehab holdback opened.
- M 1Demo & rough-ins
Demo complete, framing / roof / MEP rough-ins. Draws #1–2.
- M 2Drywall & exterior
Drywall, insulation, exterior finishes. Draw #3.
- M 3–4Interior finishes
Kitchen, baths, floors, trim, paint. Draw #4.
- M 5Punch & list
Punch list, final inspection, list on MLS. Draw #5.
- M 5–6Sale or BRRRR refi
Sell to retail buyer OR refi into 30-year DSCR loan to hold.
Four ways to exit a flip
We underwrite to your primary exit but we always pressure-test a backup. If DOM stretches or the retail market softens, the BRRRR takeout is often the cleanest fallback.
List on MLS, sell to owner-occupant. Best margins, longest DOM. Plan on 30–90 days from list to close.
Stabilize, lease, refinance into a 30-year DSCR loan at up to 75% of ARV. Pull most of your cash back out, keep the asset.
Sell to a cash investor at a small discount to skip the retail listing period. Lower proceeds but 15–30 day close.
Advanced play — sell under a lease-to-own arrangement. Higher price, longer collect, more complex documentation.
What we verify on your rehab GC
Underwriting reviews your GC package before we issue the commitment. Have these ready to speed the file.
- Active state GC / builder license (or handyman license where allowed for cosmetic scope)
- General liability insurance ≥ $1M and workers' comp on file
- 3+ verifiable references from flips completed in the last 24 months
- Written fixed-price rehab contract with scope of work per room
- Detailed line-item budget mapped to the draw milestones
- Realistic build schedule with weekly critical-path milestones
- Lien waivers collected at every draw (conditional + unconditional)
- Photos + addresses of 2+ recent finished flips of similar scope
Sample $300K ARV flip
Illustrative only — your project's split will vary by market, scope, and hold time. Contingency and holding costs are required line items on every underwritten file.
| Line item | Amount | % of total cost |
|---|---|---|
| Purchase price | $180,000 | 60% |
| Rehab budget (materials + labor) | $65,000 | 22% |
| Holding costs (IO interest, tax, insurance, utilities — 6 mo) | $16,000 | 5% |
| Closing costs (acquisition + refi/sale) | $10,000 | 3% |
| Selling costs (agent, title, transfer — ~8% of ARV) | $24,000 | 8% |
| Contingency (10% of rehab) | $6,500 | 2% |
| All-in project cost | $301,500 | 100% |
| Projected sale (ARV) | $300,000 | Contract with a real retail buyer |
| Projected gross profit | ~$28,500 | Before financing interest and income tax |
Flip loan vs. hard money vs. HELOC
Same deal, three financing paths. Speed, leverage, and how draws work drive most flippers to a dedicated fix & flip line.
| Feature | Fix & Flip loan | Local hard money | HELOC / cash |
|---|---|---|---|
| Down payment / cash-in | 10% purchase + soft costs | 20–25% + all rehab up-front | Home equity dependent |
| Rehab funding | 100% of budget in draws | Draws (higher rate) | Lump sum, borrower funds |
| Draw turn-time | 3–7 days after inspection | 5–10 days | N/A |
| Qualification | Experience + credit + reserves | Asset-based, credit-lite | Personal DTI + home equity |
| LLC vesting | Yes | Yes | No — personal only |
| Speed to close | 10–15 business days | 5–10 days | 30–45 days |
| BRRRR refi built in | Same-lender DSCR takeout | Requires re-shop | N/A |
Fix & flip terms
The vocabulary underwriting, appraisers, and title use. Learn it once and every future file moves faster.
Appraised value assuming the property is fully renovated. Flip loans typically cap at 70–75% of ARV — usually the binding leverage limit.
Loan amount ÷ acquisition price. Experienced investors can hit 90% LTP; first-time investors 80%.
Loan amount ÷ (purchase + rehab + soft costs). Typically capped at 85–90%.
The most you should pay: (ARV × 70%) − rehab − holding − selling costs − target profit. The 70% rule.
Portion of the loan reserved for the rehab budget and released in inspector-verified draws — never fronted.
Monthly interest-only payment on the average drawn balance during the rehab and hold period.
How long the finished property sits before going under contract. Every extra 30 days is real IO carry + tax + insurance.
Refinance out of the flip loan into a 30-year DSCR permanent loan once the property is stabilized and leased — the exit for buy-and-hold investors.
Number of documented flips completed in the last 36 months. Tiers unlock better pricing and higher LTP/LTC caps.
How long the loan must be in place before you can refi into a DSCR loan — typically none on same-lender BRRRR, 3–6 months elsewhere.
Ready to fund your next flip?
Send the purchase price, rehab budget, and ARV — a licensed loan officer reviews the scenario, usually the same day.
Get your Fix & Flip Deal Analysis
Send us the property and rehab budget — we send back a full flip underwriting: ARV, max loan to purchase, 100% rehab draw schedule, projected profit, and cash-on-cash return.
- ARV & max loan to purchase (up to 90% LTP)
- 100% rehab budget with draw schedule
- Projected net profit & margin
- Cash-on-cash and annualized return
Illustration only, generated from the information you enter. Not a loan estimate, pre-qualification, commitment to lend, or approval. Formal pricing, LTV, and terms are issued only after credit review, income/asset documentation, and full underwriting.
Benefits and trade-offs of a Fix & Flip loan
- 10-day closings — competitive at auction and against cash offers.
- Rehab budget fully funded on inspector-verified draws.
- Interest charged only on drawn balances.
- No prepayment penalty — exit whenever the flip is ready.
- Seamless BRRRR takeout into a 30-yr DSCR loan.
- First-time investors welcome on cosmetic rehabs with 720+ credit.
- Higher rates than long-term DSCR (9.5–13.5%).
- Origination fees of 1.5–2.5 points.
- Rehab draws require third-party inspections — build into your schedule.
- ARV cap is the binding limit on thin-margin deals.
- Extensions carry a re-price if the flip runs long.
Get your Fix & Flip Deal Analysis
Send us the property and rehab budget — we send back a full flip underwriting: ARV, max loan to purchase, 100% rehab draw schedule, projected profit, and cash-on-cash return.
- ARV & max loan to purchase (up to 90% LTP)
- 100% rehab budget with draw schedule
- Projected net profit & margin
- Cash-on-cash and annualized return
Illustration only, generated from the information you enter. Not a loan estimate, pre-qualification, commitment to lend, or approval. Formal pricing, LTV, and terms are issued only after credit review, income/asset documentation, and full underwriting.
Fix & Flip loan worked example
A flipper buys a distressed single-family for $200,000. Rehab budget is $50,000. ARV comes in at $340,000. He has 3 completed exits and 720 credit.
- Purchase price
- $200,000
- Rehab budget
- $50,000
- ARV (as-repaired)
- $340,000
- Purchase advance (90%)
- $180,000
- Rehab funding (100%)
- $50,000
- Total loan exposure
- $230,000
- ARV cap (75%)
- $255,000
- Purchase cash-in (10%)
- $20,000
- Rehab held in escrow
- $50,000 (released in draws)
- IO payment @ 11% on $180K (day 1)
- ≈ $1,650 / mo
- Sale at ARV, less 8% costs
- ≈ $312,800 net
- Gross profit before holding costs
- ≈ $62,800
Outcome: Deal works within the 75% ARV cap ($230K < $255K). Investor is in for ~$20K cash + monthly IO during the flip; projected ~$62K gross profit before holding costs.
Illustrative only. Not a rate quote, lock, offer, or commitment to lend. Binding terms appear on your Loan Estimate.
Fix & Flip loan process: from scenario to close
- STEP 1Deal review
Send address, purchase, rehab budget, and ARV comps.
- STEP 2PoF letter
Proof-of-funds letters issued same day once your file and asset docs are in for offers and auctions.
- STEP 3Appraisal / BPO
As-is + ARV valuation, 5–7 business days.
- STEP 4Close & fund
Purchase funded; rehab escrowed for draws.
- STEP 5Rehab & exit
Draws every 2 weeks; sell or refi at completion.
Get your Fix & Flip Deal Analysis
Send us the property and rehab budget — we send back a full flip underwriting: ARV, max loan to purchase, 100% rehab draw schedule, projected profit, and cash-on-cash return.
- ARV & max loan to purchase (up to 90% LTP)
- 100% rehab budget with draw schedule
- Projected net profit & margin
- Cash-on-cash and annualized return
Illustration only, generated from the information you enter. Not a loan estimate, pre-qualification, commitment to lend, or approval. Formal pricing, LTV, and terms are issued only after credit review, income/asset documentation, and full underwriting.
Fix & Flip loan document checklist
Here's what to have ready when you apply. Missing items can be added during processing — but a complete file closes faster.
- Government-issued photo ID for every guarantor
- Entity docs — Articles, Operating Agreement, EIN, Good Standing
- Purchase contract or auction confirmation
- Detailed rehab budget (scope of work + line-item costs)
- GC bid / signed contract (if using a third-party contractor)
- Comparable sales (3 recent ARV comps within 1 mile)
- Investor experience schedule (previous flips: addresses, purchase, ARV, sale price)
- Two months asset statements showing reserves + rehab escrow gap
- Homeowners / Builder's Risk insurance quote
- Title commitment through an approved title company
- Contractor's insurance certificates (GL + workers' comp)
Fix & Flip loans in Florida, Colorado, and LLC-eligible states
Simply Approved Mortgages LLC (NMLS #2620881) is a mortgage broker, not a direct lender, and arranges residential mortgage loans in Florida and Colorado. Fix & Flip business-purpose loans may be arranged in additional states only where permitted by applicable law and pursuant to applicable licensing requirements or exemptions.
Fix & Flip loan questions, answered
The questions investors ask us most — plus the exact answers we give on the phone.
How many flips do I need under my belt?
None for a cosmetic, non-structural rehab: first-time investors qualify with 720+ credit at lower leverage (typically 80% of cost, 100% of rehab, 65% ARV — 70% with one completed exit) and a budget under $250,000. Structural or gut rehabs require at least 2 completed projects in the last 3 years. Six or more completed projects unlock maximum leverage.
What's the fastest you can close?
10 business days on a clean file with clear title and a completed appraisal or BPO. Proof-of-funds letters issued same day once your file and asset docs are in letters for auction bidding.
Is there a prepayment penalty?
No. Sell or refinance any time inside the 12-month term with no exit fee.
Do you fund the rehab labor?
Yes — up to 100% of the rehab budget, released in inspector-verified draws every 2 weeks.
Can I be my own contractor?
Yes on smaller SFR projects if you have documented construction experience. Larger projects and all 2–4 unit builds require a licensed third-party GC.
How does BRRRR takeout work?
Finish the rehab, place a tenant, then refinance into a 30-year DSCR loan. Same lender means same file — takeout typically closes in 10 business days.
What's the ARV cap and why does it matter?
Total loan is capped at 75% of the after-repair value (65–70% for first-time investors). On a thin-margin deal it's the binding constraint — even if the cost and rehab math allow more.
How are draws inspected?
Third-party inspection with photos, plus a lien waiver from the GC. Funds wire within 24 hours of sign-off.
What credit score do I need?
660 minimum on most tiers; 700 is required for the highest-leverage cosmetic programs and 720 for first-time investors.
How high are the origination fees?
Typically 1.5–2.5 points depending on experience, leverage, and total loan size.
What if the rehab runs over budget?
Overruns come from your reserves first; then optionally a supplemental draw request that requires a new inspection and possibly a new appraisal.
Do you lend on auction properties?
Yes — we issue same-day PoF letters and can close in 10 days once title is clear. Auctions with 21-day timelines are standard for us.
Which calculators should I run before financing a rental?
Start with the DSCR calculator to test rent against the payment, then the cap rate calculator for the unlevered yield, the cash-on-cash return calculator for the levered year-one return, and the ARV calculator when the plan involves a rehab. All outputs are illustrative estimates, not an approval, an offer of credit, or a commitment to lend.
Do the calculators work for every state?
No. Results are shown only for the states where we arrange financing, where Simply Approved Mortgages LLC arranges business-purpose investment property financing. Selecting any other state withholds results — the check runs on our servers and fails closed.
Can I share or save my calculator results?
Yes. Every calculator produces a share link that encodes the scenario inputs only — names, emails, phone numbers, and addresses are never included — plus a copy-to-clipboard summary of the key numbers you can paste into an email or a deal memo.
What is Simply AI and can it approve my loan?
Simply AI explains the figures already shown on the page in plain English. It provides educational explanations only, does not quote rates, does not confirm eligibility, and cannot approve financing. Rates, eligibility, fees, and terms are subject to verification and change — speak with a licensed loan originator before making a financing decision.
Government & regulatory references
Independently verify program rules and consumer protections.
Related programs & tools
Run the numbers on your Fix & Flip deal
Free calculators for the metrics underwriting actually looks at, plus side-by-side deal comparisons. All outputs are illustrative estimates and are not an approval, offer of credit, or commitment to lend.
Whole-deal underwriting: PITIA, DSCR, NOI, cap rate, cash-on-cash and refinance proceeds.
Test rent against PITIA and see the ratio a lender underwrites to.
Year-one levered return on the cash you actually put into the deal.
NOI, unlevered yield, and implied value at your target cap rate.
Comp-based after-repair value with the 70% rule and profit projection.
Model the rehab loan and the DSCR refinance in one place.
The monthly rent required to reach a 1.00, 1.10 or 1.25 ratio.
Full monthly PITIA — principal, interest, taxes, insurance and dues.
LTV, CLTV, equity, and proceeds available at your target leverage.
Proceeds, new payment, DSCR impact and break-even in months.
Cash to close: fees, prepaids, escrow reserves and credits.
Cash flow, DSCR and principal paydown side by side.
Cost of a step-down prepay at your planned exit year.
Investor metrics for the markets where we arrange financing.
Deal comparisons
- DSCR Loan vs BRRRR Strategy
- DSCR Loan vs Fix & Flip Loan
- DSCR Long-Term Rental vs Short-Term and Mid-Term Rental Financing
Program availability, leverage, and terms vary by state and program. Business-purpose, non-owner-occupied investment property only; owner-occupied use is not supported. Simply Approved Mortgages LLC is a mortgage broker and arranges — but does not make — loans. Equal Housing Opportunity.
Get your Fix & Flip Deal Analysis.
Send us the property and rehab budget — we send back a full flip underwriting: ARV, max loan to purchase, 100% rehab draw schedule, projected profit, and cash-on-cash return.
- ARV & max loan to purchase (up to 90% LTP)
- 100% rehab budget with draw schedule
- Projected net profit & margin
- Cash-on-cash and annualized return
Illustration only, generated from the information you enter. Not a loan estimate, pre-qualification, commitment to lend, or approval. Formal pricing, LTV, and terms are issued only after credit review, income/asset documentation, and full underwriting.
Get your personalized investor loan quote
Pick the loan type that fits your deal and complete a short, tailored pre-qualification. A licensed loan officer follows up with an initial scenario review once we have your credit authorization and supporting documents — usually the same business day. Formal pricing and terms follow underwriting.
Pick a loan type
You can change this any time.Tell us about your scenario
The form below is tailored to DSCR rental loan — only the questions your program needs.